


Since I left Chile for good in February 2020, I have gone back more often than I planned. In August I even went for one week, as I explained here.

I was an Entel guy, but I admit that every time I land I buy a prepaid plan from WOM: CLP 4,999 a month for 50GB, about five US dollars. That is crazy compared to Canada, where I pay C$60 ($42 USD) a month for the same plan!
Chile was not always like this. Before 2016 the top data plans cost over CLP 30,000 a month and Entel was printing cash. It paid that excess out as dividends year after year. That left the door open for a fourth player to come in and start a price war.
Well, that is what happened.
In January 2015 Novator bought Nextel Chile for US$35m. On July 7, 2015 it relaunched the company as WOM, with prices up to 40% lower and ads that mocked the incumbents by name. WOM’s first customers even rode on Entel’s network, because few phones in Chile worked on WOM’s frequency and their calls and data passed to Entel under a contract Nextel had signed.
By the end of 2023 WOM had 8.5 million customers and ranked second in mobile connections. It paid for the war too. It filed for Chapter 11 in April 2024 and came out in 2025 with new owners. The prices never went back up. Entel’s own CFO says Chile has the second-lowest price per gigabyte in the world. That is the market Entel lives in, and it is the backdrop for what happened this week.
On Monday Entel [ENTEL.SN] jumped about 20% to its highest price since 2019. I had bought it the Thursday before, and I told you so in Weekly #108, where I joked that somebody would shout “inside information”.

So let me tell you where the inside part comes from. It is about fifteen years old.
In the early 2010s I was at Moneda when Entel hired me as Director of Strategic Planning and Corporate Development. It meant stepping outside the capital markets. I took the job because I would run the strategy and do M&A, and I was curious about how a deal looks from inside the company instead of from the buy side.
Funny enough, almost everything Entel has executed since then was part of the playbook I developed there: sell the infrastructure, keep the customer. The towers went to American Tower [AMT 0.00%↑] in 2019. The data centers went to Equinix [EQIX 0.00%↑] in 2022. The fiber network went to ON*NET Fibra, owned by KKR [KKR 0.00%↑] and Telefónica [TEF 0.00%↑], the same year. Last Friday, Peru went to Millicom [TIGO 0.00%↑].
Here is where the board and I parted ways, then and now. I never argued for paying most of that money out as dividends.
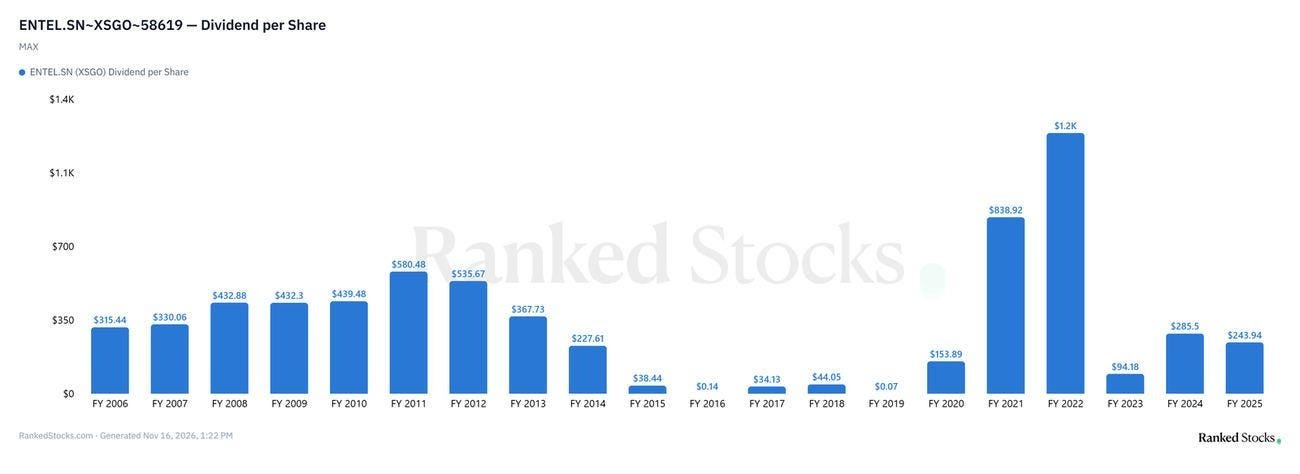
I argued for spending it on the moat: the network, the fiber, the things a customer would miss if he left. That is the part Entel has not done well.

I thought the lesson had landed after WOM. Entel paid out almost everything it earned in the fat years, then a price war arrived and it had to ask shareholders for money. But teaching new tricks to old dogs is hard, and a CLP 2,100 dividend is on its way.
One more thing before the numbers, because I owe it to the place. My time at Entel was the most enjoyable of my working life. It is the only place where I did not run into toxic coworkers. Well…maybe one or two.
Besides the nice work environment, I learned a lot there. I saw every type of telecom asset, from cable companies to data centers (something I have relied on heavily when digging into the data center thesis for the AI theme), and more abstract valuations such as broadband spectrum. Those were fun times that I still cherish.
This post is free and belongs to my Chilean Stocks series. Entel is not in the Beating the Tide portfolio. It is what I do with my own money in Chile, so you will not find a rating here. You will find my fair value, CLP 6,700 a share, and the question I have not seen anybody answer: what the dividend costs you in tax, and whether you should take it at all.
TLDR
Entel [ENTEL.SN], Chile’s largest mobile operator, agreed to sell Entel Perú to Millicom for US$1,714m. The cash Entel receives, about US$1,400m, equals 90% of its market value the day before the announcement.
Peru produced 34% of group EBITDA and 19% of the cash left after leases and capital spending. Entel sold the hungry half at 5x EBITDA while Mr. Market paid about 3x for Chile.
My fair value is CLP 6,700 a share against a price near CLP 6,000, or 12% higher. Bear case CLP 4,950, bull case CLP 10,000.
Shareholders vote on November 30 on a special dividend of CLP 2,100 a share. A Chilean resident in the top bracket hands 646 of those pesos back as tax. Selling before the record date and buying back after costs me about 158.
In the 13.5% bracket or below, the dividend comes with a tax refund. Take it.
Gains on Entel shares sold from January 1, 2027 are tax free in Chile. Sales in 2026 pay 10%. That shapes when I sell.
Entel sold the infrastructure that used to be its moat. What is left is a premium brand and 240 MHz of spectrum under a cap of 264.
I will vote for the sale on November 30 and I recommend you do the same. The main risk is that it does not close.
Table of Contents
The Chilean telecom industry: four players, the cheapest prices in the region
Where the money goes: the controller, the moat, and my old argument