


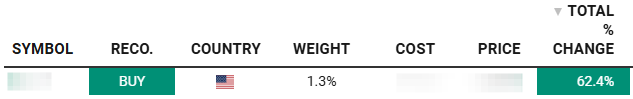
The position is up +62% since I picked it in May 2025. My position has not changed, and neither has my $67 target.
If you missed the beginning, here is the original May 2025 pick.

The idea was straightforward: a customer service outsourcer was winning business, improving its delivery model, and using AI to make its offering more useful.
The latest earnings give that thesis more substance. Revenue hit another record, new client wins accelerated, and management expects another year of growth. But Q4 also exposed that more revenue did not translate into more operating profit.
Behind the paywall, I revisit the original thesis, walk through the presentation’s AI case studies, and explain why I still rate the shares BUY. I also separate the promising industry trends from the ways automation could hurt the economics.