


Usually I don’t go to networking events, and now even less than I used to. But in July I went to an informal CFA Toronto gathering for drinks. I had a nice time and ended up chatting with a portfolio manager focused on US financials.
I asked for his top pick; it was WFC. I asked him why, and he gave me his elevator pitch. In his pitch he was comparing all the US large-cap financials on the same metric, but I knew that one of those companies wasn’t really comparable because of what sits in its capital structure. I asked him about it, and he brushed off my question with an ambiguous non-answer that sounded smart.
Anyways, I kept thinking about it, as this company has been staring at me for months on my screener, so I took a deeper look and lo and behold…it became the September Stock Pick.
That capital structure question turned out to be the whole thesis. Every valuation has one input that does most of the work, and it is almost never the one people argue about.
I ran 100,000 simulations on this month’s pick, and then I looked at which assumption was actually moving the output. Nine of every ten dollars of dispersion came from a single number: the rate I use to discount the company’s future profits back to today. The earnings path, the payout, the growth rate, the terminal assumption, all of them together accounted for the rest.
So I went looking for who else was making this argument, and the answer is nobody. Mr. Market is valuing this bank on a multiple of next year’s earnings, on a chart, on a quant score. Where a discount rate does get named, it arrives asserted, with no beta, no build-up and no justification of any kind, and then the argument moves straight back to the earnings forecast.
I have been skeptical of the megabanks for years, for the reason McKinsey put plainly in this year’s Global Banking Annual Review: banking carries the lowest price-to-book and price-to-earnings ratios of any industry on earth, and it has for a very long time. Millions of people pricing an industry that low for that long is a verdict about required returns. The question I set out to answer this month is whether that verdict applies to this particular bank, and my answer is that it does not.
First I will explain what the business actually does and where the earnings come from. Then I will walk through the engine that I think the market is underrating, which is mechanical rather than cyclical and runs for five more years. Then we will do the real work on the discount rate, three different ways, and check it against what the company’s own capital stack is telling us. Finally I will put the whole thing through the model, steel-man the case against me, and give you the number.
So earlier today, I sent an email to paid subscribers with the trade alert.
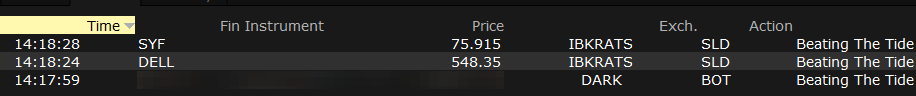
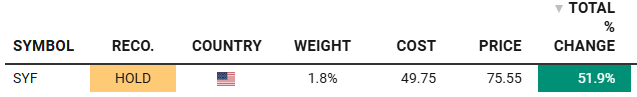
I closed SYF and locked a 52% gain.
And financed the gap by trimming a bit more from DELL.
Later next week, I will be sending a post-mortem on SYF.