I was almost certain the November pick would be a copper company. I told you so in Weekly #108, and I spent the first half of the month inside copper names. At the end I was in between FCX and ERO. I ended up scratching that (maybe for the December pick) and bought a copper company in my Chilean portfolio, and may end up writing about the rationale if I have time next week.
I opted for something else. I’m constructive on the copper price over the medium and long term, but I see no catalyst for it in the short to medium term, so owning a miner today would leave me depending on the fundamentals of the metal and nothing else. The company I bought doesn’t need a commodity to cooperate. It rents its buildings, spends less than a cent of every revenue dollar on capex, and grew sales by more than a quarter last quarter in an industry that sold less than it did a year ago.
That industry lives off the US housing market, and housing is in its deepest slump in sixteen years. Existing-home sales fell to a 3.75M annual rate in October, the lowest since August 2010. You’d expect a company selling into that to shrink. This one has landed above the top of its own revenue guidance fifteen quarters in a row.
Mr. Market still prices it for 4% growth a year. That is the growth rate today’s share price implies in my model. My base case uses 9%, and I think the gap exists because the stock gets valued on a multiple of next year’s earnings and a balance sheet that screens as debt-free, when the two questions that decide what it’s worth are how much debt sits in its leases and what discount rate a business like this deserves.
I’m closing the DXP Enterprises [DXPE 0.00%↑] position to pay for this one, as I flagged in Weekly #108.


I locked the 60.7% gain on DXPE. I still see upside in DXPE, but its reward to risk is not that attractive anymore, which makes it the best position to redeploy into the November pick.

Below the paywall you get the name, the model, the business explained in plain English, the windfall inside this year’s margins that I expect to fade, and what I think a share is worth.
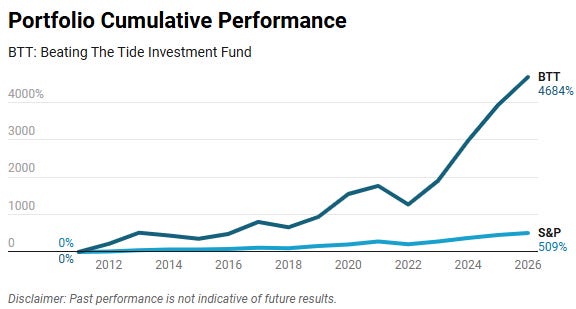
The chart below is the portfolio these picks go into: up 4,684%, against 509% for the S&P 500 over the same period.